FLOW · Week Ending November 1, 2026
The Week Wall Street South Happened: FLIBS Closes with €1.4B Afloat, the Fed Holds 10-2 With a Hawkish Lean, and Florida's Election Day Arrives Tuesday
The Wall Street South Summit concludes at FLIBS, the Federal Reserve holds with a hawkish lean, and Florida's election approaches as Brickell transactions, RIA consolidation and Q4 capital allocation take center stage.
Full report
FLOW — Florida Financial Intelligence Week Ending November 1, 2026 The Week Wall Street South Happened: FLIBS Closes with €1.4B Afloat, the Fed Holds 10-2 With a Hawkish Lean, and Florida's Election Day Arrives Tuesday The week that Florida's financial leadership has been building toward delivered on every dimension. The 67th Fort Lauderdale International Boat Show closed Sunday after five days with 182 superyachts and a combined €1.4 billion in brokerage inventory across six waterfront venues — the largest floating display of investable assets in North America. The Wall Street South Summit ran through the show, putting hedge fund managers, RIA principals, family office allocators, and institutional investors in the same physical spaces where the portfolios they manage are expressed as 34-meter teak-decked structures. The Federal Reserve held rates at 3.75–4.00% Wednesday in a 10-2 vote, with Fed Chair Kevin Warsh describing the meeting as "a heck of a family fight" and delivering a tone that markets read as setting up a December hike at 85% probability. And Florida's governor race reaches its conclusion Tuesday — with Byron Donalds at +4 in the polling average and Ken Griffin's $10 million bet on the outcome of the most consequential state policy decision for the Florida institutional investment ecosystem in a generation.
THE WALL STREET SOUTH SUMMIT — FLIBS WEEK DEBRIEF
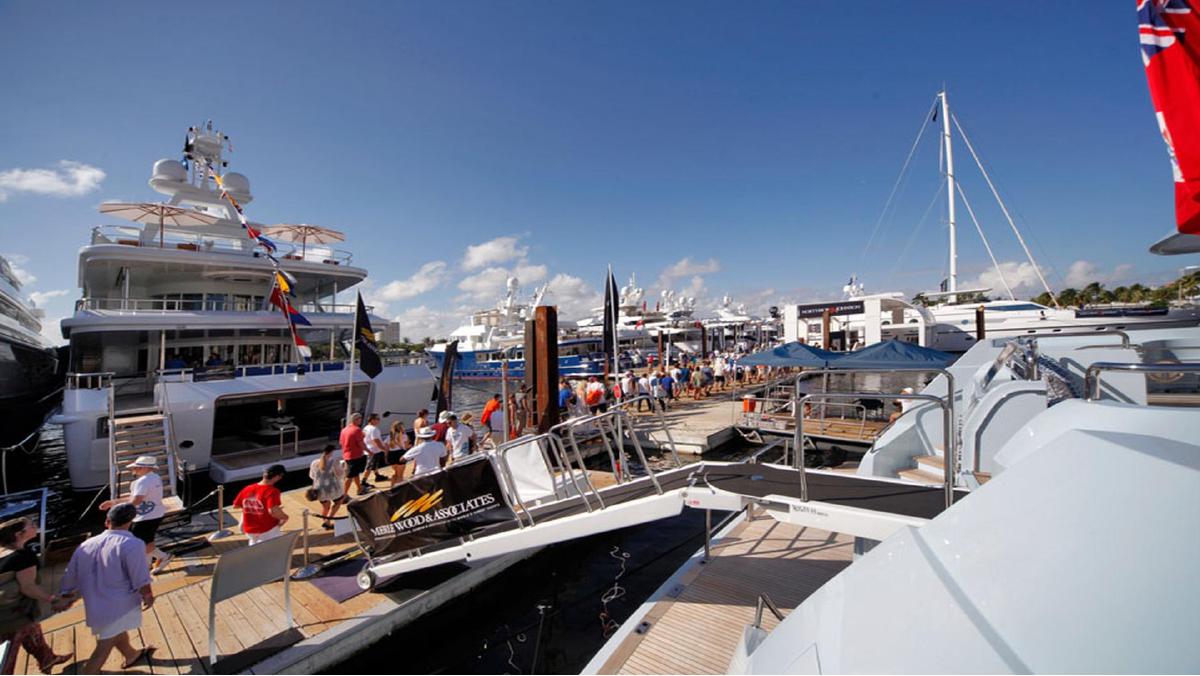
The Wall Street South Summit completed its run at the 67th Fort Lauderdale International Boat Show this week, anchoring five days of institutional relationship-building against the backdrop of the largest floating display of investable assets in the Western Hemisphere. The Summit convened hedge fund managers, RIA principals, family office allocators, and institutional investors across six Fort Lauderdale waterfront venues — Bahia Mar, Las Olas Marina, Hall of Fame Marina, Pier 66 Marina, Superyacht Village, and FLIBS Yacht Club — during a week when the Federal Reserve simultaneously delivered its most anticipated rate decision of the year.
The convergence that FLOW flagged last week proved to be exactly the catalyst it appeared: the FOMC held rates on Wednesday afternoon, the Warsh press conference ran through the market close as the Summit's first full day was underway, and the conversations about portfolio construction, December hike probability, and Q4 allocation decisions happened in real time between the people who make them. This is the structural advantage of the Wall Street South Summit format: it compresses into five days, on a waterfront setting that no hotel ballroom replicates, the kinds of candid peer-level conversations that institutional relationships are built on. The allocators who were there are now three conversations ahead of the ones who weren't.
FLIBS itself validated the thesis. Boat International confirmed 182 superyachts in attendance with a combined brokerage asking price exceeding €1.4 billion. The fleet spanned 6,174 meters with an average length of 33.95 meters — a show dominated by the sub-40-meter institutional buyer class that represents the crossover between UHNW personal capital and the liquidity events that create it. Six hundred-plus exhibiting companies across six venues, with Fort Lauderdale's marine economy estimated to generate over $12 billion annually, made this the week's most concentrated expression of the Florida capital formation thesis: the wealth created in and attracted to Florida is now large enough to sustain its own ecosystem of institutional services, real estate, yachting, and financial advisory.
The Wall Street South Golf Day is the Summit's next convening — a single-day, invitation-only round at a premier South Florida course that continues the extended institutional conversations FLIBS started. Deal flow, co-investment structures, LP introductions: the Golf Day is the round two of the relationships that were initiated on the water this week. Registration is open now at www.wallstreetsouthsummit.com. Spots are limited to the same caliber of attendees who made FLIBS week the defining event of Florida's Q4 institutional calendar.
FOMC HOLD: DECEMBER HIKE AT 85%, WARSH SIGNALS A SERIOUS FIGHT
The Federal Reserve held rates at 3.75–4.00% on October 28 in a 10-2 vote — the closest Fed vote in this cycle. Governor Lisa Cook and Cleveland Fed President Beth Hammack both dissented in favor of a 25- basis-point hike, a public signal of how close the committee came to moving. Chair Kevin Warsh described the meeting as "a heck of a family fight" and "a serious, sober discussion," language that was immediately read by markets as confirmation that the December meeting will be live.
The statement upgraded economic growth from "solid" to "strong" while noting that "inflation remains elevated" — a hawkish combination that kept the 10-year Treasury above 5.00% (touching 5.042% intraday) and drove December hike probability to approximately 85% on futures markets. The 2-year yield briefly reached 4.774% before pulling back to 4.70%. Gold fell 0.40% to $4,058. The dollar eased modestly, with EUR/USD near 1.1135. Equity markets absorbed the news with minimal disruption: S&P 500 +0.10% to 7,730.
The implications for the Florida commercial real estate market are direct and immediate. The floating-rate debt that underlies the transitional office assets now being repriced in Brickell — including the comps set by the 701 Brickell close at $443 million and the 801 Brickell process now in market — prices off the forward curve that Warsh's hawkish tone just steepened. The refinancing window for assets with near-term debt maturities is now shorter than it appeared at the September meeting. For the private credit managers who gathered at FLIBS this week, the Warsh press conference was as consequential as any panel session: a hold with hawkish forward guidance is the signal that December's decision will set the rate environment for Q1 2027 underwriting.
Warsh also announced a structural change to the FOMC's meeting schedule beginning in 2027: strategy-only meetings with no rate vote will be added to the calendar. The change is operationally significant for institutional managers with annual investment policy reviews tied to the Fed calendar — it adds meeting dates that will generate market movement through expectation management without the binary outcome of a vote.
FLORIDA CAPITAL FLOWS
The 801 Brickell office tower process — the next major transaction test after the 701 Brickell close at $443 million — is now fully in market. Monarch Alternative Capital and Tourmaline Capital Partners, which acquired the 412,000-square-foot tower in 2023 for $250 million, are running a sales process through Eastdil Secured and Savills targeting a price that would set a new Florida per-square-foot office record if achieved. The 701 close at $644 per foot is the current benchmark; the 801 ask is undisclosed but is understood to target a higher number. The critical market question the 801 process will answer is whether the Brickell institutional buyer pool is one transaction deep or several. If it clears at or above the 701 comp within 60 to 90 days, the repricing of Brickell's trophy office market is structural. If it stalls or clears at a discount, the market is acknowledging that the international buyer appetite — GCC sovereign capital, European family offices, LATAM institutional — is not yet deep enough to sustain sequential record transactions.
Ken Griffin's Citadel is now in active crane procurement for its $2.5 billion, 1,046-foot supertall headquarters at 1201 Brickell Bay Drive — seeking what would be the tallest construction cranes ever deployed in Florida history. The procurement process, reported by CoStar, is the first concrete signal that the project has moved from entitlement to mobilization. Groundbreaking, originally targeted for late 2025 and later revised to mid-to- late 2026, has not yet been confirmed; the crane procurement suggests the timeline is tightening toward a Q1 2027 mobilization at the current pace. The 54-story, 1.7-million-square-foot Foster + Partners design was approved by Miami-Dade and received FAA clearance to 1,049 feet. Citadel employees currently occupy 830 Brickell and Southeast Financial Center in the interim. When Griffin breaks ground on a $2.5 billion headquarters on an entire Brickell city block, it will be the most consequential single construction commitment in Miami's history — and the physical expression of the Wall Street South thesis that Florida is not a satellite market for New York capital, but a primary one.
The RIA M&A market's 2026 trajectory is now confirmed by Fidelity's midyear data: assets involved in acquisitions nearly doubled to $343 billion in H1 2026 — an 88% increase — even as deal count fell 9% to 120 transactions. The story is concentration: fewer deals, far larger. The median acquired RIA grew from $517 million to $630 million in AUM. Private equity-backed buyers now represent 89% of transactions, up from 86% a year ago. For Florida-based managers, this data confirms the direction that the WEG auction has been signaling: the consolidation premium for independent RIAs with proven client retention, strong revenue multiples, and UHNW concentration is at a historical peak. The WEG process — still unresolved between Carlyle and Bain Capital — will set the reference multiple that Florida's independent advisory community prices itself against.
The WEG Wealth Enhancement Group auction remains in final bid stage with no winner announced. Carlyle and Bain Capital have submitted final bids in a Goldman Sachs and Evercore-run process, but the sellers — TA Associates and Onex — retain the option to hold the business. The $7 billion valuation target implies a revenue multiple that would be among the highest in RIA secondary history. With a year-end close targeted, the November timeline is now the critical path: a signed deal before Thanksgiving would validate the multiple. A decision to hold, or a bid that fails to clear the seller's expectation, would be the most significant data point against the premium-consolidation thesis in a year of otherwise confirming evidence.
FLORIDA GOVERNOR RACE — ELECTION DAY TUESDAY
Florida's gubernatorial election between Republican Byron Donalds and Democrat David Jolly resolves Tuesday. As of October 31, PollCheck's polling average has Donalds at 48.1% and Jolly at 44.0% — a 4- point lead — with Donalds at 90% win probability. The most recent survey, an ActiVote poll of likely voters conducted October 20-31, showed Donalds at 52.3% to Jolly's 47.7%. Individual late-October polls range from Donalds +9 (co/efficient) to Jolly +2 (Workbench Strategy), reflecting a genuinely competitive race in a state that has consistently elected Republican governors since 1999.
For Florida's institutional investment community, the gubernatorial outcome has direct policy implications across four categories. First, carried interest taxation at the state level: Florida has no state income tax, but any shift in corporate structure requirements, partnership registration treatment, or professional services tax policy flows through the governor's office. Second, SBA investment mandate: the governor sits on the State Board of Administration's Board of Trustees alongside the Chief Financial Officer and Attorney General. The incoming governor will shape the SBA's alternatives allocation philosophy and its stance on emerging and diverse manager programs. Third, insurance investment constraints: Florida's insurance commissioner is appointed by the governor, and the investment guidelines for Florida-domiciled insurance companies are an important secondary capital pool for alternative strategies. Fourth, Opportunity Zone and enterprise zone policy: Florida's OZ program direction is gubernatorially influenced and has produced some of the highest- performing OZ investments in the country — managing that program's next chapter is a governor-level decision.
Ken Griffin's $10 million contribution to Byron Donalds in July was the largest single donation to the race. Griffin's electoral engagement reflects the broader dynamic that FLOW has been tracking: the financial leadership that has relocated to Florida from New York, Chicago, and Greenwich is now engaged in the state's political environment with the same conviction they have brought to its commercial real estate and financial markets. The outcome of Tuesday's election is the first major test of whether that financial community's political engagement translates into electoral influence.
BANKING / INSURANCE / PRIVATE CREDIT
The December FOMC hike probability at 85% — established by Warsh's hawkish hold — is the most important single variable in Florida's commercial real estate credit market between now and year-end. The Brickell office repricing thesis that the 701 close confirmed depends on a stable or declining rate environment over the 2-to-5-year hold periods that characterize the current buyer pool: Elliott, Morning Calm, Monarch, Tourmaline are all managers whose return profiles require rate certainty, not rate acceleration. A December
hike would compress the cap rate arbitrage that makes $640-per-foot Brickell trophy office financeable at current leverage ratios. Private credit managers who were at the Wall Street South Summit this week are adjusting their term sheets accordingly.
The Florida insurance investment market enters Q4 with a double catalyst: the approaching November Atlantic hurricane season close on November 30 and the governor's race on Tuesday. Florida's insurance market has been in structural distress since 2022 — Citizens Property Insurance's depopulation program, the reinsurance market repricing, and the legislative changes to assignment of benefits and litigation reform have improved the market's fundamental structure but not yet resolved the availability crisis in coastal markets. For institutional managers with ILS and reinsurance exposure, Florida's November 30 season close is the portfolio event; the gubernatorial outcome is the 12-month policy signal.
The Florida SBA enters its most consequential Q4 allocation cycle in recent memory. The $294 billion total portfolio — with commitments of $727.7 million to real estate in recent cycles and $1.3 billion to alternatives in Q4 2024 alone — is now the defining institutional LP signal for Florida-based alternative managers. The Q4 2026 pacing decisions across private equity, real assets, and hedge funds will be influenced by a new governor's policy direction, the December FOMC outcome, and the rate environment Warsh established this week. For managers with active SBA relationships, the November Trustees meeting is the most important meeting of the year. For managers without existing SBA relationships, the informal engagement window that precedes the formal RFP cycle is now at its annual inflection.
DEAL RADAR
Deal / Event Detail Wall Street South Summit — FLIBS week Five days at 67th FLIBS; 182 superyachts; €1.4B brokerage fleet; six Fort concluded Lauderdale venues; Fed hold delivered Day 1; Golf Day next — www.wallstreetsouthsummit.com FOMC October 28 — hold 10-2, December hike Rate held at 3.75–4.00%; Cook + Hammack dissented for hike; Warsh called at 85% it "a heck of a family fight"; 10-yr Treasury hit 5.042%; December hike probability 85% 801 Brickell — record price process in market Monarch Alternative + Tourmaline selling 412K sqft; Eastdil + Savills advising; undisclosed ask above 701's $644/sqft comp; $250M basis in 2023; market test of Brickell depth Citadel — crane procurement signals $2.5B, 1,046-ft Foster+Partners HQ at 1201 Brickell Bay Drive; tallest cranes construction approach in FL history sought; FAA-approved; groundbreaking approaching Q1 2027 RIA M&A — assets nearly doubled in H1 2026 Fidelity: $343B in acquired assets (+88%); deal count -9% to 120; median acquired RIA $630M; PE buyers 89% of transactions; WEG still unresolved WEG auction — Carlyle vs. Bain, year-end $7B valuation; $160B AUM; Goldman + Evercore; TA Associates + Onex close targeted selling; no winner yet; decision expected before year-end Florida governor race — Election Day Donalds at +4 in polling average (90% win probability); Griffin $10M donor; November 3 SBA, insurance, OZ, carried interest implications for FL institutional managers Florida SBA — Q4 allocation cycle most $294B portfolio; $1.3B to alternatives in Q4 2024; Q4 2026 pacing decisions consequential in years influenced by new governor, December rate path, and Warsh's hawkish signal December FOMC — 85% hike probability set Warsh hold + hawkish tone; 2-yr Treasury to 4.774%; S&P 7,730 +0.10%; December decision sets Q1 2027 underwriting environment for FL CRE credit
3 STRATEGIC INSIGHTS FOR MANAGERS
1. The Wall Street South Summit Proved the Thesis — Now the Golf Day Is the Follow-On The Wall Street South Summit at FLIBS delivered exactly what FLOW has been arguing it would: the concentrated, high-quality institutional relationship-building that defines the next decade of Florida capital formation, compressed into five days on a superyacht-lined waterfront during the most consequential Federal Reserve week of the year. The managers who were there made LP introductions, co-investment conversations, and deal flow relationships that no conference room replicates. The Wall Street South Golf Day is the designed follow-on — the setting where those relationships convert from introduction to structure. Co-investment proposals, LP commitments, and deal partnerships that began on the FLIBS docks in October close on South Florida fairways in November. Registration is at www.wallstreetsouthsummit.com. The calendar of Florida institutional events does not offer another convening of this caliber until Art Basel in December. The Golf Day is the room between now and then.
2. Warsh's Hawkish Hold Is the Single Most Important Variable in Florida CRE Credit for Q4 The Warsh hold was not a neutral event. A 10-2 vote with two members voting for an immediate hike, an upgrade of growth to "strong," and a statement that "inflation remains elevated" has set December hike probability at 85%. For Florida's commercial real estate credit community — which spent most of FLIBS week discussing the 801 Brickell process, the Citadel construction financing, and the refinancing windows on transitional assets — this is the data point that reprices every term sheet written between now and December 10. The floating-rate debt underlying the Brickell office repricing thesis, the construction lending that Swire and Citadel are both going to need, and the securities-backed credit lines against Bezos-tier UHNW residential collateral all price off a forward curve that Warsh just steepened. The managers who built their Q4 deployment models on a hold-and-cut scenario need to rebuild them on a hold-and-hike scenario. The ones who have already done that are ahead.
3. Tuesday's Election Is Not Just a Political Event — It Is a Capital Allocation Signal The Florida governor's race resolves Tuesday, and the institutional investment community's stake in the outcome is structural, not partisan. The incoming governor shapes the SBA's $294 billion portfolio through Board of Trustees membership, sets insurance investment guidelines through an appointed commissioner, influences Opportunity Zone and enterprise zone programs directly, and establishes the regulatory environment for the independent RIA and family office markets that are the growth capital source of Florida's financial ecosystem. Ken Griffin did not put $10 million into Byron Donalds' campaign as a political expression — he did it as a capital allocation decision, the same way he has allocated capital to Miami real estate, Citadel's Brickell headquarters, and the Tyko Capital construction lending program. The managers who process Tuesday's result as a portfolio variable — not a news event — are the ones who will be positioned for the policy implications in Q1 2027. For FLOW's institutional readership, the question is not who wins. It is: what does each outcome imply for the allocation environment you are building into?
WALL STREET SOUTH SUMMIT
ANNUAL GOLF DAY · SOUTH FLORIDA
By invitation and registration — Register at www.wallstreetsouthsummit.com
The Wall Street South Summit closed the 67th Fort Lauderdale International Boat Show with a week that defined South Florida finance for the next decade: the FOMC delivered its hold on Day 1 as 182 superyachts and €1.4 billion in floating inventory lined six Fort Lauderdale waterfront venues. The conversations between Florida's hedge fund managers, RIA principals, family office allocators, and institutional investors on those decks were the real transaction — relationships and LP introductions that no conference room replicates.
The Wall Street South Golf Day continues the Summit's mission in a different setting: an invitation-only round at one of South Florida's premier courses, designed for the extended conversations that define institutional relationships — deal flow, co-investment structures, LP commitments. Spots are limited. Managers and allocators who were at FLIBS this week know the value of being in the room. The Golf Day is the next room.
Register: www.wallstreetsouthsummit.com
FLOW — Florida Financial Intelligence is produced weekly for institutional use. Not investment advice.
FLOW · For institutional use · Not investment advice
Download full PDF ↗FIFO members get curated introductions and invitations to our private roundtables.
Apply for Membership →GET FLOW EVERY WEEK.
Florida's capital flows, talent moves and deals, in five minutes.